Pre-owned aircraft transactions: The 5% that makes every deal different
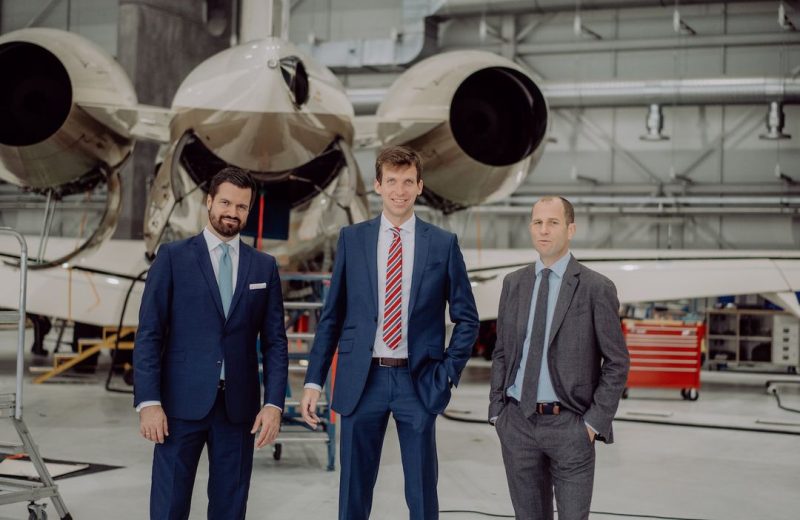
(L-R) Alexander Nefzger, Richard Prechtel and Matthias Reuleaux from Hannover-based activelaw.
Buying or selling a pre-owned business aircraft may look straightforward: agree on the aircraft, agree on the price, conduct the pre-purchase inspection, sign the documents and close. In practice, there is much more to it. Words by Richard Prechtel, partner at activelaw.
Most aircraft transactions follow a remarkably similar structure. The same documents, the same closing mechanics and many of the same regulatory and tax issues appear again and again. In our experience, perhaps 95% of every transaction is familiar territory.
It is the remaining 5% that makes each transaction different – and sometimes surprisingly complicated.
A successful transaction therefore depends not only on a well-drafted aircraft purchase agreement (APA), but on understanding from the outset how the aircraft will actually move from seller to buyer: legally, physically, technically, tax-wise and from one aircraft register to another.
Start with the LOI – and make it useful
The letter of intent (LOI) is often treated as little more than a document recording the agreed purchase price. This is a missed opportunity.
A good LOI should establish the basic architecture of the transaction before the lawyers start negotiating the APA.
In addition to the purchase price, it should address the deposit and the circumstances in which it is refundable or non-refundable. It should identify the intended delivery condition, the proposed pre-purchase inspection facility, the anticipated closing location and the key milestones of the transaction.
Timing is particularly important.
Pre-owned aircraft transactions work best when they move quickly. The LOI should therefore set out a realistic but ambitious timetable for negotiating and signing the APA, funding the deposit, commencing and completing the PPI and proceeding to closing.
The LOI is also the right place to agree on governing law. This should not be regarded as boilerplate. The governing law can have a material impact on warranties, remedies, title transfer, termination rights and the interpretation of the final APA.
Resolving these fundamental points at LOI stage makes the subsequent contract negotiations significantly more efficient.
The APA is more than a purchase contract
Once the commercial terms are agreed, attention shifts to the Aircraft Purchase Agreement.
For a pre-owned aircraft, the APA will usually contain the expected provisions on purchase price, deposit, title, risk of loss, inspection, delivery conditions, representations and warranties and the typical ‘as is, where is’ allocation of risk.
But the most important provisions are often those dealing with the mechanics of delivery.
The parties need to agree precisely what condition the aircraft must be in at delivery. This includes not only its physical and technical condition, but also its maintenance status, records, equipment, damage history and regulatory documentation.
The delivery conditions must be sufficiently precise to determine whether a discrepancy discovered during the PPI is a seller’s responsibility, a buyer’s responsibility or simply part of the commercial bargain inherent in purchasing a used aircraft.
This sounds obvious. In practice, it is one of the areas where disagreements most frequently arise, since you are talking $100,000 USD fast.
Closing location is a tax question as much as a legal one
The closing location should never be selected simply because the aircraft happens to be there.
In most business aircraft transactions, particularly cross-border transactions, the location at which title and possession pass may have significant customs and tax consequences.
Before the APA is signed, the parties and their advisers should understand where the aircraft is currently located, its customs status, where it will be delivered, who will export it, who will import it and where it will ultimately be based and operated.
Depending on the jurisdictions involved, the analysis may include VAT, import VAT, sales or use tax, customs duties, export exemptions and potential tax registration requirements for either party.
An aircraft may, for example, need to leave one customs territory in order for the seller to establish a tax-free export. The buyer may simultaneously need to arrange importation into another jurisdiction. In other cases, changing the closing location by only a few hundred miles may fundamentally alter the tax analysis.
The APA must reflect the result of that analysis.
A properly drafted tax clause should allocate responsibility for taxes, customs declarations, import and export formalities and supporting documentation. It should also address what happens if a tax authority subsequently takes a different view of the transaction.
But this leads to one of the most important lessons in aircraft transactions: the APA cannot replace transaction planning.
What is not written in the APA can be just as important
A purchase agreement may say that the seller will deregister the aircraft and that the buyer will register it in its chosen jurisdiction.
That single sentence can conceal a substantial amount of work.
The parties need to understand the de-registration requirements of the existing registry and the registration requirements of the new one. Depending on the jurisdictions involved, this may require an Export Certificate of Airworthiness, de-registration requests, releases of mortgages, discharge of other registered interests, IDERA-related documentation and coordination between aviation authorities.
The timing matters.
When will the existing registration cease? When can the new registration become effective? Who can fly the aircraft during the period in between? Is a permit to fly required? When will the Certificate of Airworthiness for Export be issued? What original documents need to be delivered and which authority requires them?
These issues may occupy only a few lines of the APA, but they can determine whether the aircraft can actually leave the closing location after title has passed.
The same applies to customs and tax planning. A contract can allocate responsibility for an export declaration, but somebody still needs to know exactly how that declaration will be made, who will act as exporter of record, which customs office will handle it and what evidence will subsequently be available to establish the export.
For this reason, seller, buyer and their respective advisers need a common understanding of the entire transaction structure well before closing.
The PPI: where the theoretical deal meets the actual aircraft
The pre-purchase inspection is often the point at which a transaction becomes interesting.
Until then, the parties have largely negotiated around a description of the aircraft. The PPI introduces the aircraft’s actual technical condition into the transaction.
A good APA clearly defines the inspection scope, the relevant delivery conditions and the consequences of discrepancies.
But no drafting can eliminate every disagreement.
A finding may technically fall outside an agreed delivery condition but still represent a significant economic issue for the buyer. Conversely, a buyer may request rectification of an item that the seller is contractually not required to remedy.
This is where transaction experience matters.
The first question is, of course, what the contract requires. The second – and often more important – question is how the parties can resolve the issue economically and keep the transaction moving.
That may involve a repair, a purchase price adjustment, an escrow holdback, a cost-sharing arrangement or simply an agreed acceptance of the discrepancy.
The objective should normally be to solve the problem, not to win an academic argument about it.
Closing preparation starts long before closing
A well-run closing should feel almost uneventful.
Getting to that point requires considerable preparation.
Once the APA has been signed and the PPI is underway, the transaction team should work systematically through the conditions precedent to closing.
Title searches must be updated. Corporate authorisations and powers of attorney must be prepared. Bills of sale, acceptance certificates and delivery receipts need to be agreed and placed in escrow where appropriate. Existing mortgages and international interests may need to be discharged, while new financing security is prepared for registration.
At the same time, deregistration must be coordinated with the existing registry and registration with the new registry. Customs brokers need instructions. Export and import declarations need to be prepared. Tax documentation must be assembled. Insurance needs to become effective at precisely the right moment.
And, of course, the PPI needs to be completed.
Any discrepancies with the agreed delivery conditions must be identified, allocated and resolved before the parties arrive at closing.
The closing checklist is therefore much more than an administrative document. It is the roadmap that brings together the contractual, technical, regulatory, tax, financing and operational elements of the transaction.
Do not negotiate the aircraft into the ground
There is a commercial reality that lawyers sometimes underestimate: an aircraft sitting on the ground is expensive.
Every additional week of negotiations may mean hangar costs, maintenance costs, financing costs, crew costs and – depending on the aircraft – substantial lost operational value.
It is therefore rarely sensible to spend weeks negotiating the final legal nuance or the last dollar of a discrepancy if a commercially reasonable solution is available.
This does not mean accepting unnecessary legal or economic risk. It means understanding the purpose of the transaction.
The buyer wants the aircraft. The seller wants to sell it. Both sides need legal certainty. But both sides also need the deal to close.
Once negotiations become entrenched, transaction fatigue can develop surprisingly quickly. A technical discrepancy becomes a matter of principle. A relatively small cost becomes a dispute. Confidence between the parties deteriorates. Eventually, one side starts wondering whether it still wants to do the deal at all.
We have seen transactions fail not because the fundamental economics were wrong, but because relatively small issues were allowed to dominate the transaction for too long.
The 95/5 rule
After working on numerous aircraft transactions, one conclusion becomes difficult to avoid: 95% of aircraft deals are essentially the same. The remaining 5% is what makes every deal different.
The aircraft may have an unexpected technical issue. A registry may require a document nobody anticipated. The intended export structure may not work. A customs authority may take a different position. The buyer’s financing may introduce an additional closing condition. A deregistration may take longer than expected. Or the PPI may reveal a discrepancy that simply does not fit neatly within the wording of the APA.
That 5% is where transaction experience becomes particularly valuable.
The answer is not necessarily a longer contract. It is having advisers who understand not only what the APA says, but how aircraft transactions actually work – from PPI and deregistration through customs and tax planning to the final release of funds and transfer of title.
A good aircraft transaction lawyer should therefore not merely document the deal. The role is to help structure it, anticipate where it may become stuck and, when the unexpected happens, find a solution that allows the transaction to continue.
Because ultimately, the best aircraft transaction is not the one in which one side won every negotiating point.
It is the one in which both parties achieved a fair and legally secure result – and the aircraft departed on time.
Experience makes the difference
At the activelaw Aviation Desk, we handle approximately 30 to 40 aircraft transactions every year, with a team of four lawyers focusing exclusively on aviation matters.
This volume of transactions has shaped our approach. We believe that aircraft deals should be pragmatic, fast-moving and carefully planned from the outset. Identifying the critical issues early, agreeing on a workable transaction structure and keeping all parties focused on the closing are often more valuable than spending weeks negotiating points that have little practical impact on the deal.
Our objective is therefore not to make a transaction more complicated than it needs to be, but to make sure that the complicated parts are identified and resolved before they become closing issues.
We are proud that we have never lost a transaction because our legal process was too slow, too complicated or too heavy. For us, that is ultimately one of the best measures of successful transaction advice.
In aircraft transactions, good legal advice should protect the client – without getting in the way of the deal.
Subscribe to our free newsletter
For more opinions from Corporate Jet Investor, subscribe to our One Minute Week newsletter.