Cooperation key to solving problems in the region, says AsBAA’s Balmer

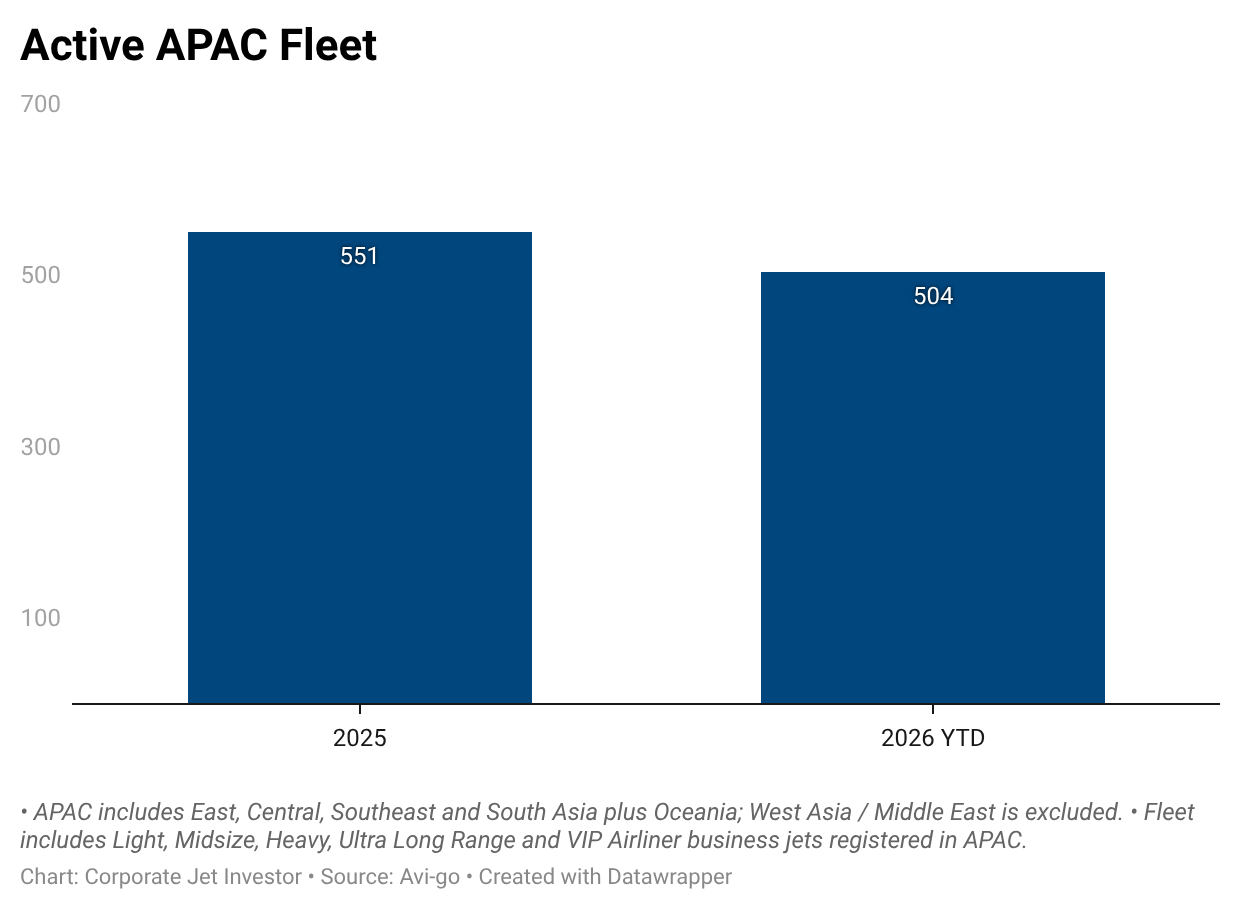
Asia’s business aviation market is complex. With a fleet of over 1,100 jets, the market serves a geographical area bigger than both Europe and North America. Business aviation firms operating in the region navigate dozens of jurisdictions, regulatory frameworks, and permit systems that were never designed with private aviation in mind.
This mismatch, the Asian Business Aviation Association (AsBAA) argues, is the root of the region’s most pressing problem

Phil Balmer
: illegal charter. Phil Balmer, head of technical at TAG Aviation and a volunteer Chairman at AsBAA, has spent more than 30 years watching the market in the region evolve from Hong Kong outward.
“We operate in a very large area with multiple jurisdictions, multiple governments, and multiple authorities,” Phil Balmer tells Corporate Jet Investor. “Any time there is a regulation that is more complicated, I think that puts pressure on the system and can drive operations underground. We want to take away any incentive for people to try and go around the system.”
The mechanics of the aviation market in Asia are straightforward. The aviation regulatory infrastructure was catered to scheduled airline operations. Permits are pre-planned for fixed routes over extended periods. Business aviation, by design, requires flexibility, speed, and the ability to change plans at short notice. Meanwhile, as the existing permit system struggles to accommodate that dynamism, some operators tend to lean on the private side of the rulebook. Instead of pursuing full commercial authority, they tend to go for a Part 91-style approval rather than going through a Part 135 commercial permit process.
Cabotage rules add another layer to that complexity. Most markets in the region prohibit foreign-registered aircraft from carrying passengers between two points within their borders, largely to protect the domestic airline industry. The rules vary considerably by country. Some nations prohibit it outright, while others allow special clearance or operate under reciprocal agreements. In general, though, an international charter looking to add a domestic leg is crossing into extremely regulated territory. Additional clearance can take days to obtain. In markets where demand is urgent, the temptation to operate informally is not difficult to understand.
For AsBAA, an association representing business and general aviation entities based in Asia, the recourse has been to engage with civil aviation authorities in the region to help redesign the permit process. “We’re actively engaging with the authorities, offering our help to say, how can we make this system faster and better,” says Balmer. “We have seen some countries that have really tried to ramp that up over time. It takes time. Everything takes time to change. But we usually see steady improvements.”
Eric Lok, AsBAA’s COO, says stamping out illegal charter is the association’s top mission alongside ensuring safety. He says they consistently engage with travellers, encouraging them to ensure the operator they use holds a valid Air Operator Certificate before booking. This may seem obvious in markets like the US or Europe, but in parts of Asia, the line between a private owner carrying a passenger informally and a commercial operator is not always clear.
The illegal charter problem does not exist in isolation. It is a symptom of a market that has grown substantially but unevenly constrained by geography, regulation, and a commercial aviation infrastructure that has historically absorbed demand that in other markets would flow naturally toward the business jet charter market.
The region’s fleet of approximately 1,100 aircraft is spread across a vast and fragmented market. Southeast Asia remains buoyant, with Singapore and Hong Kong being the most operationally flexible jurisdictions for charter.

China’s trajectory has seen the most dramatic shift over three decades. Prior to around 1998, business jets in China were largely confined to state-adjacent or mission-specific use, with Air China Business Jet operating what Balmer recalls as a Learjet 45 followed by a Gulfstream IV among the earliest examples of anything resembling commercial business aviation activity. Balmer points out that “prior to that, the business jet activity in China was pretty much just mission-specific and not really utilising business aviation travel as a tool.”
The market that exists today, with Gulfstream and Bombardier both holding strong positions and Embraer carving out strength in Indonesia, bears almost no resemblance to where the region started.
Vietnam is emerging as a new source of demand, driven by its growing role as a foreign direct investment and manufacturing destination. Indonesia’s 7,000-island archipelago creates a structural case for air travel that road and rail cannot address. Penang generates consistent corporate traffic on the back of its semiconductor manufacturing base.
The common thread across all these markets is that business aviation’s value is indirect and therefore consistently underappreciated by governments that judge airports on duty-free revenue and landing fees, rather than on the investment and employment created by the passengers arriving on those jets.
“The people that are flying in the business jets are the ones that are investing in the country; they’re creating jobs, they are creating economic prosperity,” says Balmer. “That is a value to the country that you won’t see in the profit and loss of an airport, but it’s critical to the economic prosperity of those countries.”
Maintenance is another critical piece in Asian business aviation that has evolved alongside the market. Two or three decades ago, sending a business jet to the United States or Europe for heavy maintenance was common practice. It was an economically rational decision: labour costs in the Asian region were high, capabilities were limited, and the ferry cost of flying an aircraft to the US or Europe was offset by savings on the other end. “When you’re doing 5,000 man-hours, it actually made economic sense to take the aircraft outside of Asia,” says Balmer.
But that mathematics has since shifted substantially. MRO capabilities across Asia have expanded. OEM parts warehouses have been established at nearly all key hubs. The post-Covid surge in US business aviation activity has pushed American MRO capacity to a premium, eroding the pricing advantage that once made transatlantic maintenance worthwhile.
“The MROs are very full, very tricky to get slots,” Balmer says of US maintenance capacity. “So their labour rates over time have crept up.” Balmer describes the evolution of the maintenance market in Asia as an economy-of-scale story. “As the fleet has grown, the infrastructure has followed,” he notes, adding that “the capabilities and the pricing disparity have definitely reduced” over the years.
Singapore remains the main hub for parts and maintenance support. “It is the biggest aviation hub from the perspective of maintenance and support shops in the region,” says Balmer. Hong Kong also retains meaningful infrastructure. China has developed in-house capabilities, including Bombardier’s facility in Tianjin, which Balmer says is “up there” in terms of regional support.
On the parts supply chain, Balmer says post-Covid bottlenecks have been resolved significantly, with exceptions for only a few specific models. “I feel like that bottleneck has mostly been removed,” he says. “There are still a few parts issues around the place depending on the aircraft model and the part, but generally we’ve had a pretty good improvement over the years and certainly you can have that part in your hands within several hours.” Overall, the disruptions of the post-Covid period have given way to a functional parts network in which urgent components can reach most major Asian hubs rapidly.
Asked whether Asian customers approach business aviation differently from their European or American counterparts, Balmer says: “Business aviation is their time machine. They’re made to create time, give that flexibility, plus on top of that, there’s extra security, there’s privacy,” highlighting that for these clients, the jet provides an essential corporate edge. For many owner-operators in the region, leisure use simply doesn’t feature. “They never use it for that. It’s just 100% business all the time,” he says. The aircraft is there to do a job.
This framing of business aviation also helps the association make its case with governments and regulators who remain sceptical of an industry they associate with luxury rather than economic utility. AsBAA’s advocacy work is essentially an exercise in reframing – shifting the conversation from what business aviation costs a jurisdiction to what it generates for one.
With Southeast Asia consolidating its position as a manufacturing and investment hub amid broader geopolitical shifts, the association believes the underlying demand case has never been stronger.
The task now is ensuring the regulatory environment catches up fast enough to keep that demand above ground.
Subscribe to our free newsletter
For more opinions from Corporate Jet Investor, subscribe to our One Minute Week newsletter.